A year-end business finance review brings your existing borrowing and your 2027 cash flow forecast together. Start by identifying when repayments, renewals and balloon payments fall due, then check whether your facilities can cover planned investment and periods when cash is tight.
At Charles & Dean, we look at how these commitments overlap. A vehicle finance agreement, commercial mortgage and working capital facility can each serve a different purpose, but the repayments all come out of the same cash flow.
What should a year-end business finance review cover?
List each facility's outstanding balance, interest rate, repayment schedule, fees, maturity date and any security or personal guarantees. For revolving facilities, include the credit limit and how much is currently drawn. Flag fixed-rate expiries, renewal dates and balloon payments. If you're considering repaying a facility early, ask the lender for a settlement figure and check how long it's valid.
Plot these payments against your monthly cash flow forecast, alongside VAT, payroll, stock purchases and planned capital expenditure. Test what happens if a major customer pays a month late. Check your lowest projected cash balance and how much undrawn credit would be available at that point.
Which commercial finance agreements should you review?
- Asset Finance: Check when agreements on vehicles, machinery and equipment end, whether there's a final payment and when assets are due for replacement. If you're considering asset refinancing, calculate the net proceeds after settling existing finance and deducting fees. Explore asset finance and asset refinancing.
- Working Capital and Business Loans: If you pay suppliers before customers pay you, estimate the size and duration of that cash gap. Check available credit limits, interest charges and whether scheduled loan repayments fit the months when cash is tightest. Explore business loans.
- Commercial Mortgages: Check when the fixed rate expires and when the loan matures. Model how a rate change would affect monthly repayments. If refinancing is needed, check potential valuation and legal costs, alongside any early repayment charges. Explore commercial mortgages.
When is it worth refinancing existing business debt?
Refinancing replaces existing borrowing with a new agreement. It's worth comparing terms when a facility is approaching maturity, repayments no longer fit your cash flow or the business needs capital for a specific investment.
Compare the remaining payments on your current agreement with the full cost of the proposed facility, including any final payment, settlement charges and fees. If settlement costs are rolled into the new borrowing, account for them in the new repayment schedule.
Check how the new terms affect any security or guarantees. Extending the term can reduce monthly repayments but increase the total you pay.
Read the British Business Bank's guide to refinancing and business debt consolidation.
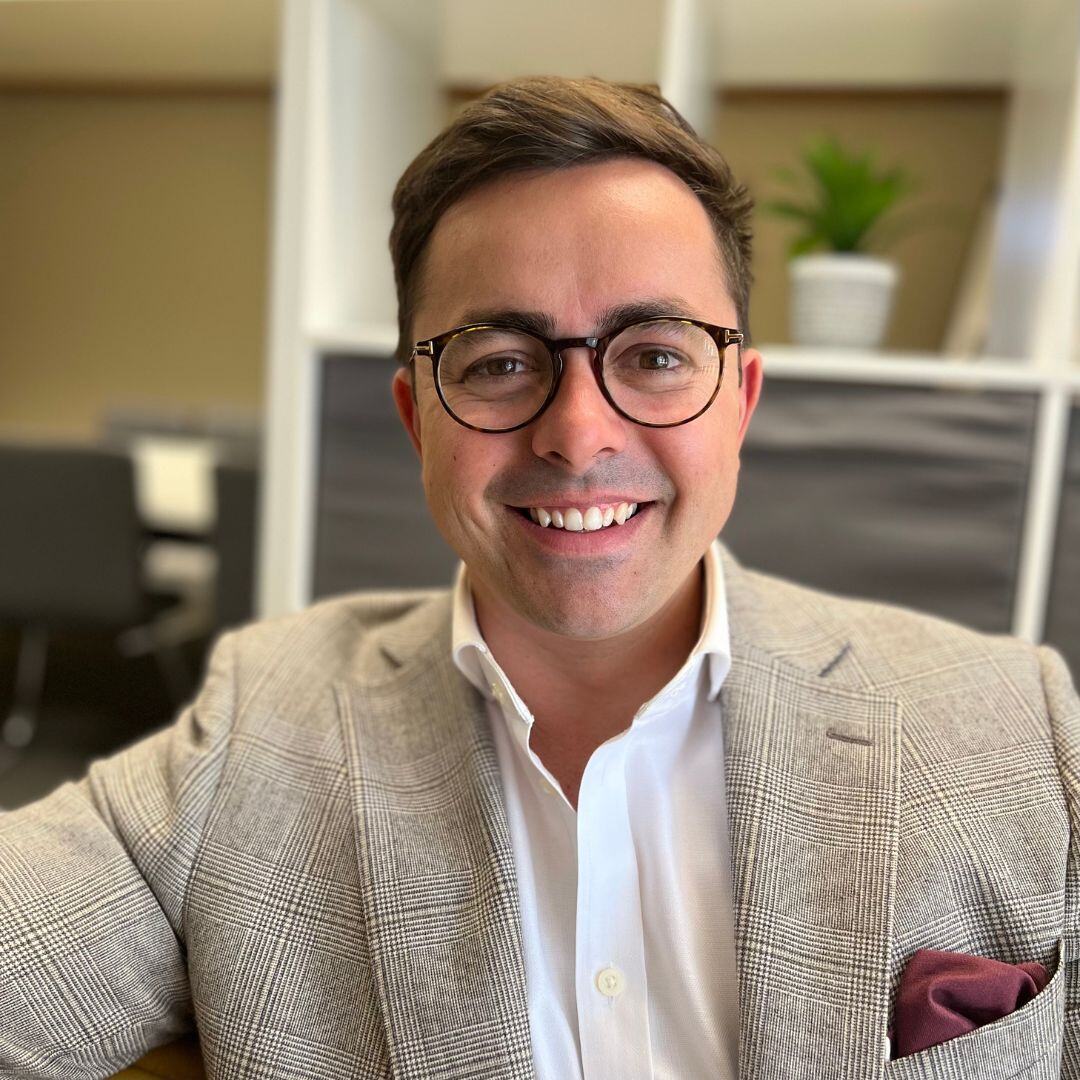
Tom Perkins, Co-Founder of Charles & Dean, said:
"We’re speaking with SMEs about restructuring existing debt as some high street banks become more selective about who they lend to. If your borrowing costs have risen or a facility is coming up for renewal, it’s worth checking whether the terms still work for your business. We know the UK lending market and how different lenders assess a business. That allows us to compare what’s available and assess whether a different lender could offer a more competitive rate or a repayment structure that better fits your cash flow.”
How can a commercial finance broker help?
Before heading into 2027, review your existing finance arrangements and consider whether your borrowing could work harder for your business.
As a commercial finance broker, Charles & Dean can use your existing agreements, cash flow forecast and funding plans to compare options from our lender panel.
If a facility is due for renewal or you're planning an investment in 2027, bring your repayment schedule and details of the amount and timing of any additional funding you need.
Speak to our Business Finance Team on 01780 763836 or request a quote online.
Tom Perkins
Director & Co-Founder of Charles & Dean
For over ten years, Tom has been a noteworthy leader in the asset finance space, delivering talks and sharing knowledge across a plethora of platforms. We know him to be an influential figure when it comes to disrupting outdated trends and driving finance for SMEs across the UK. His ever-present dynamism permeates even the farthest branches of the Charles & Dean community, inspiring our endeavour to provide unique, tailored solutions.


 Sport & Performance
 Luxury & Prestige
 Supercars
 Classic & Motorsport
 Porsche
 Ferrari
 Land Rover
 Lamborghini
 BMW
 Mercedes-Benz


 Agriculture
 Leisure & Hospitality
 Construction
 Manufacturing & Engineering
 Commercial Vehicles
 Transport & Logistics
 Food & Beverage
 Utilities & Waste